
Azerbaijan’s Absheron gas project: economics behind $4.2 billion investment
Qabil Ashirov
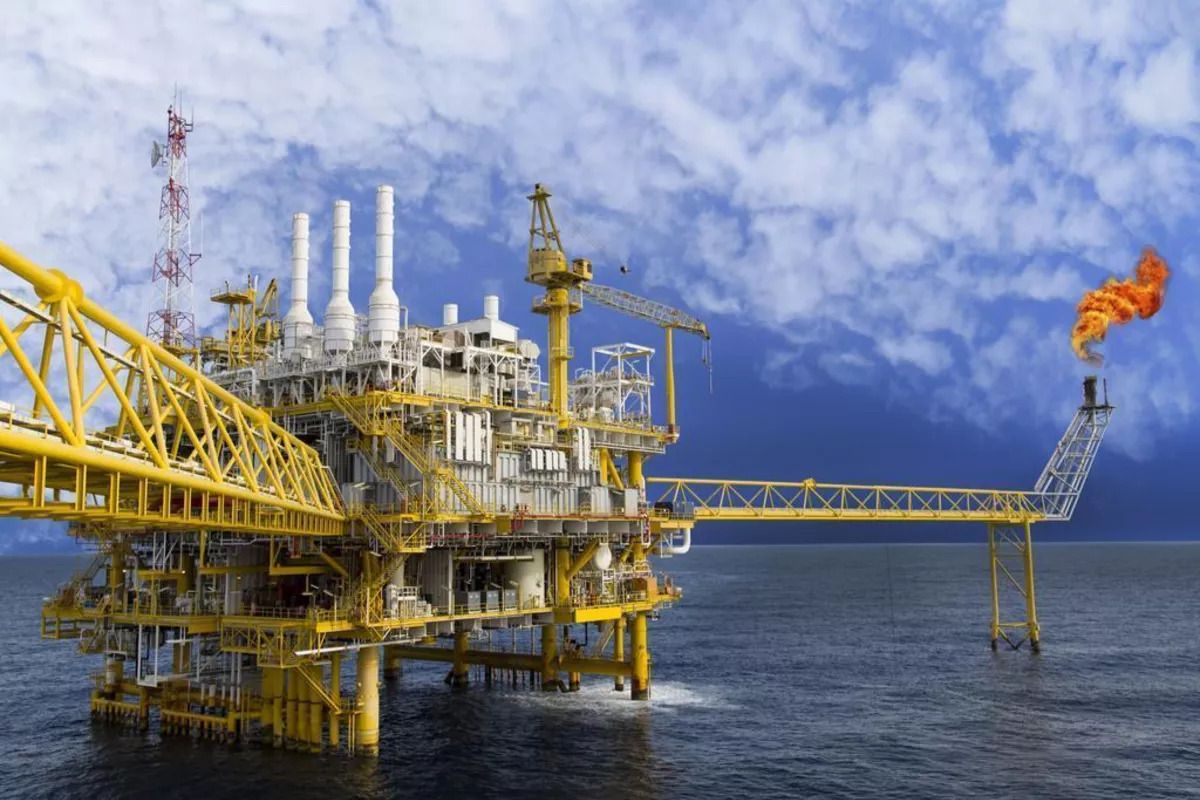
Read moreA new major investment phase is beginning in Azerbaijan’s energy sector. The adoption of the final investment decision on the full-scale development of the Absheron gas-condensate field could turn the project into one of the main sources of Azerbaijan’s gas production and export capacity in the coming years. Capital investment of approximately $4.2 billion is involved, and the main question is how much economic value this investment will create for Azerbaijan.
The recoverable gas reserves of Absheron are estimated at approximately 140 billion cubic meters. The first phase of the field came on stream in 2023 and has the capacity to produce 1.5 billion cubic meters of gas per year and 12,000 barrels of condensate per day. The new Full Field Development phase will increase the field’s total gas production to 6 billion cubic meters per year and condensate production to 47,000 barrels per day. The new phase is expected to come on stream in 2029.
The key figure here is the additional 4.5 billion cubic meters of gas. This is a significant volume for Azerbaijan’s gas market. In a simple calculation, if the average selling price of 1,000 cubic meters of gas is $200, the annual gross sales value of 4.5 billion cubic meters of gas could amount to approximately $900 million. If the price is $250, this figure would rise to $1.125 billion, and at $300, it would reach $1.35 billion.
However, Absheron’s economic potential is not limited to gas. The second phase of the project is planned to produce approximately 35,000 barrels of condensate per day. This amounts to approximately 12.8 million barrels per year. If the average price of condensate is assumed to be $60, its annual gross sales value could reach approximately $767 million. Thus, purely for illustrative purposes, in a scenario where the average gas price is $200 and the condensate price is $60, the annual gross product value of the new phase could be approximately $1.67 billion.
Here, however, an important warning is necessary: $1.67 billion is the theoretical sales value of the product. Production and operating costs, transportation, maintenance, taxes and other payments must be deducted from this amount. In addition, the project’s revenues are divided among the partners according to their respective shares. Currently, SOCAR and TotalEnergies each hold a 35% stake, while XRG holds a 30% stake.
From this perspective, Azerbaijan’s revenue does not automatically mean 35% of the project’s total revenue. SOCAR will receive revenue according to its share, while the state may receive additional revenues through taxes and other economic mechanisms. Therefore, when assessing Absheron’s real impact on the Azerbaijani economy, it is not sufficient to look only at the market price of gas.
On the other hand, Absheron strengthens Azerbaijan’s domestic gas supply. Gas produced during the first phase is directed to the domestic market. Following the new phase, the gas is planned to be supplied both to the domestic market and exported to Türkiye. According to the information provided, exports will provide access to the Turkish and European gas markets through the existing infrastructure.
This is particularly important for Azerbaijan. As we know, gas exports also determine Azerbaijan’s role in the regional energy system. The additional volumes from Absheron could help support the country’s gas portfolio against changes in production from other fields over time.
On the other hand, the payback period for the $4.2 billion investment remains one of the key economic questions. For example, if the annual gross product value of $1.67 billion mentioned above were simply divided mechanically by $4.2 billion, the result would be a period of slightly more than 2.5 years.
A proper economic assessment would need to take into account the project’s operating costs, the production profile over the years, gas and condensate prices, taxes, the partners’ financing shares and the revenue-sharing terms of the contract.
This is precisely where Absheron’s main economic story lies. Azerbaijan is not investing $4.2 billion in infrastructure simply to produce another 4.5 billion cubic meters of gas. The aim is to turn existing gas reserves in the Caspian Sea into a long-term commercial asset, strengthen domestic supply and create additional volumes for export.
If gas and condensate prices remain favorable, Absheron could generate billions of dollars in additional product turnover for Azerbaijan over the coming decades. The key question, however, is how much of this gross value will be converted into net profit, and how much will accrue to SOCAR, the state budget and the Azerbaijani economy as a whole. These indicators will ultimately determine the real economic outcome of the $4.2 billion investment.
Here we are to serve you with news right now. It does not cost much, but worth your attention.
Choose to support open, independent, quality journalism and subscribe on a monthly basis.
By subscribing to our online newspaper, you can have full digital access to all news, analysis, and much more.
You can also follow AzerNEWS on Twitter @AzerNewsAz or Facebook @AzerNewsNewspaper
Thank you!