
$15bn promise: Can Baku, Ankara turn their energy alliance into trading powerhouse?
Akbar Novruz
Read moreAzerbaijan and Türkiye have been talking about their economic partnership as if it were already an integrated industrial system. Oil flows to the West, gas is transported across the Anatolian steppe, and Azerbaijani money is reshaping part of the Turkish Aegean coastline. But the most telling number isn’t that of the capacity of an oil refinery. It is the gap between what their neighbors currently trade and what they wish they traded tomorrow.
The value of bilateral merchandise trade amounted to $5.72bn in 2025, based on data from Azerbaijani customs. The political goal is to have trade at $15bn. This means a 162% increase would be needed, not just yet another meaningless agreement or the passing of a couple more trains across the border. The real question is how 'wide' the perspective is.
The capital link is truly significant, undoubtedly. Estimates of total direct investments into Türkiye reached by $21.1bn over the period of 1995-2025, while investments into Azerbaijan have amounted to $18.4bn. These are historical investment numbers and not a reflection of the annual bilateral trade turnover. They do not indicate that Azerbaijan is the biggest foreign investor in Türkiye either. However, they illustrate the development of the partnership beyond official proclamations.
Yet, the trade link is less impressive. In January-July 2026, two-way merchandise trade amounted to $3.28bn and decreased 3 per cent compared to the corresponding period last year. Azerbaijani exports into Türkiye decreased 2.9 per cent, whereas imports from Türkiye were 3.2 per cent lower than last year. There could be various reasons behind year-to-year fluctuations, including energy prices, composition of the shipment and competitive exporters. Nevertheless, if the partnership wants to increase its turnover almost threefold, the shrinkage should be reversed first.
When an Azerbaijani-owned plant in İzmir sells its output to a Turkish customer, it may create industrial value and profits for its owner without adding a dollar to Azerbaijan–Türkiye merchandise trade. Investment and trade reinforce one another, but they are not interchangeable statistics.
SOCAR offers an industrial blueprint
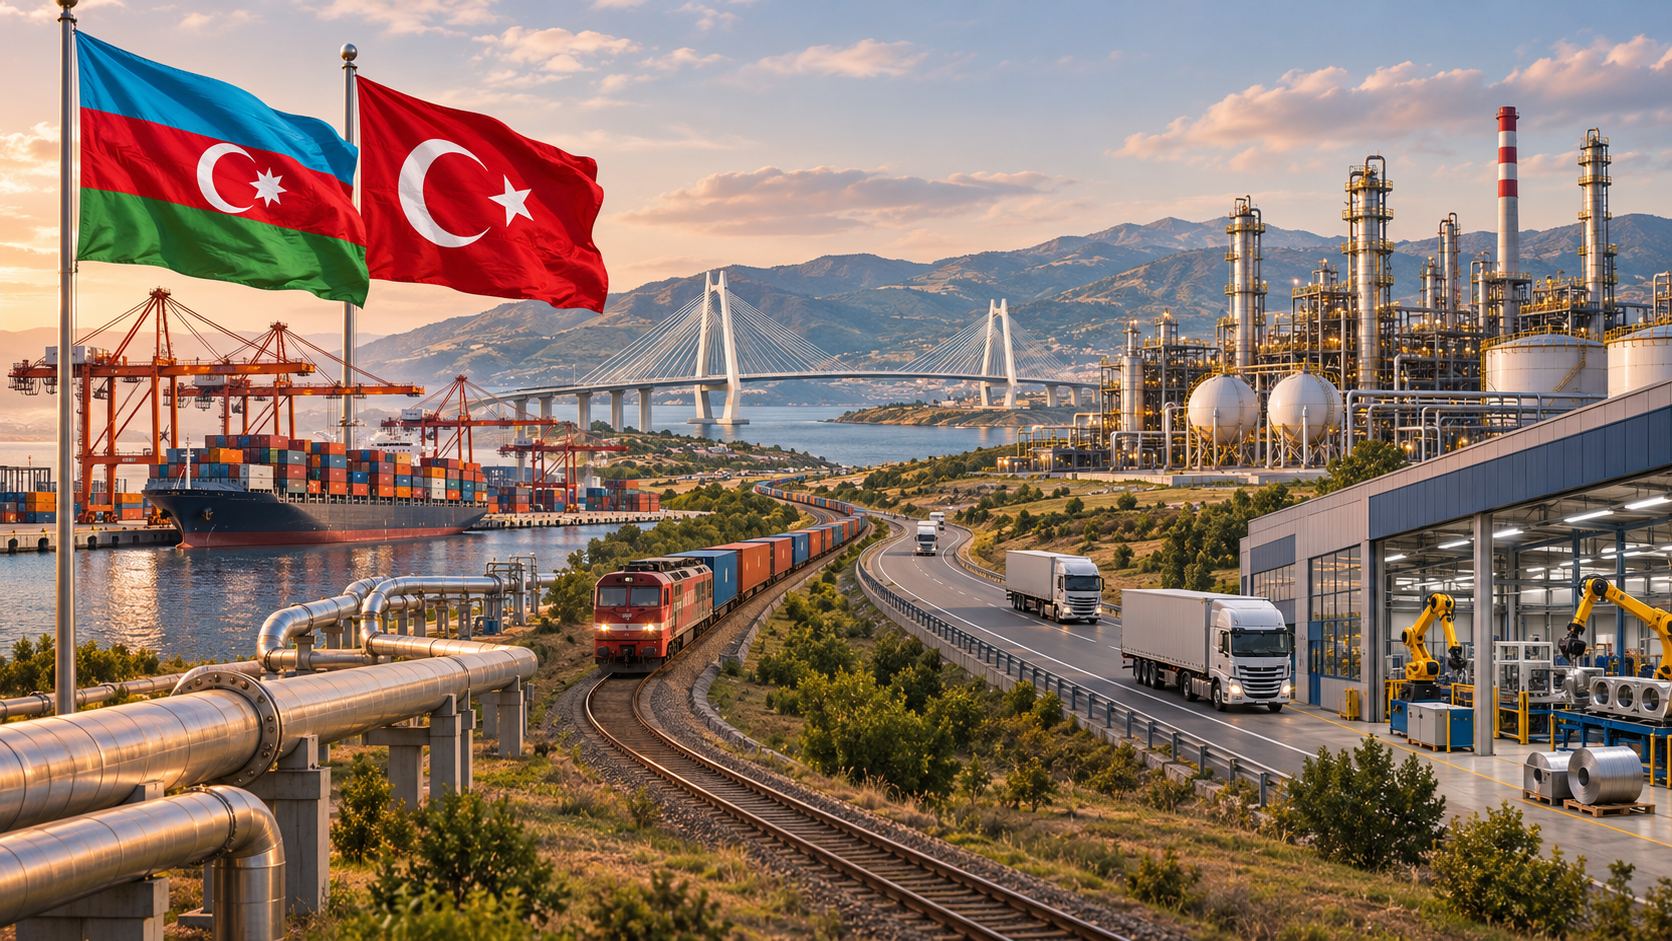
However, proof of economic integration can be found in Aliağa, where a new $6.3bn refinery project of SOCAR called STAR Refinery serves as the hub of a refining and petrochemical complex surrounding the Petkim. Recently, SOCAR announced another TL6bn investment in a jet-fuel unit project aimed at creating room for 600,000 tonnes more diesel per year. Its completion is scheduled for early 2029.
Petkim’s bigger gamble remains a bit of an “if”. The company has ordered some $70mn worth of engineering and design in support of a petrochemicals development program which will seek to increase polymer output more than twice. While Technip Energies has been awarded the technology and engineering contracts, the design studies are to continue all the way up until late 2027 ahead of any potential final investment decision. An engineering contract is not the same as the finished plant—and an export sale either.
The $1.6bn funding agreement reached by SOCAR Türkiye in October is another good example. This re-finances existing debts via a syndicate of 22 banks, rather than being $1.6bn worth of newly committed industrial investment. The true potential lies in getting companies on both sides to develop supply chain activities around chemicals, plastics, components, and special services where products cross borders and not just hands.
Perhaps the trade policy needs a wider doorway...
Nevertheless, the regulatory framework is still limited compared to the rhetoric. An agreement of preferences for trade took effect in 2021 and will expand in July 2024. As was reported by a trade officer from Türkiye in December 2025, preferences apply to about 30 goods but may cover up to 50. This is good, but limited considering the $15 billion goal.
Some additional tariff preferences could help farmers, food processing and selected manufacturing companies. Still, other factors matter for industrial investors – certification, customs procedures, rules of origin, payment terms, and speed of clearance of shipments. The regulation of digital services and engineering projects needs its own set of regulations. Their addition to a list of goods preferred cannot alone ensure the flows of such services.
The 110-point bilateral agenda reached in December 2025 indicates that governments understand the scope of the challenge. The piece of the puzzle that is lacking in public ambition is the scorecard: what barriers have been removed, what industries have placed orders, and what additional non-oil trade has resulted from the effort?
Corridor outlook
The alternative route through the Syunik area in Armenia, referred to as the Zangezur Corridor and established under the TRIPP initiative, can eventually become a more direct link from mainland Azerbaijan, Nakhchivan, and Türkiye. In 2025, Ankara started the construction of a 224 km-long railway from Kars to Iğdır–Aralık-Dilucu, whose budget is estimated at €2.4bn. The Armenian-US model provides connectivity, retaining control by Armenia. Yet the design, financing, border processes, and construction process remain key limiting factors.
According to the World Bank’s September 2026 assessment, better-connected trans-Caspian transport corridors can triple the capacity of trade routes and cut down travel time in half by 2040. These are conditional forecasts for the region, not projections of trade between Azerbaijan and Türkiye. Fast transit makes trade more affordable but does not automatically create demanders, industries and goods.
The fees received for transiting Chinese or Central Asian cargo should not be considered to be goods transported between Baku and Ankara. The most valuable aspect of the transit route might be its indirect impact – ensuring that factories can rest assured that their parts or products will reach the destination market.
Real test of $15bn promise
Aiming at such a high figure is undoubtedly bold, but the initial conditions for achieving the goal have rarely been more favorable. Rarely does any two-state relationship benefit from having made commitments in capital on the level of SOCAR, physical energy connections, and a political environment conducive to enhanced business cooperation. While these conditions do not ensure the delivery of goods, they offer a foundation for doing so.
Opportunities can arise from ongoing initiatives: expansion in petrochemical capacity in the region of Aliağa, connections among companies that provide support to refineries and production facilities, preferential trade agreements, and, if plans for additional connections come to fruition, transport lines directly linking Azerbaijan, Nakhchivan, and Türkiye. These initiatives would open up opportunities not just for energy companies, but also for small-scale manufacturers, logistics companies, and technology firms.
Getting to $15 billion will, of course, take continued growth at something like 21 percent annually starting from 2025 if the goal is to be realized by 2030, an arbitrary time frame and not a firm deadline. But the potential goes far beyond any such benchmarks. As has been shown by both Azerbaijan and Türkiye, the possibility for strategic interests to lead to investment in infrastructure and industry is there. The logical follow-up would be to take that success further into a wider commercial relationship based on energy.
Here we are to serve you with news right now. It does not cost much, but worth your attention.
Choose to support open, independent, quality journalism and subscribe on a monthly basis.
By subscribing to our online newspaper, you can have full digital access to all news, analysis, and much more.
You can also follow AzerNEWS on Twitter @AzerNewsAz or Facebook @AzerNewsNewspaper
Thank you!