
Azerbaijan’s manat faces global dollar surge with $15 bln buffer
Qabil Ashirov
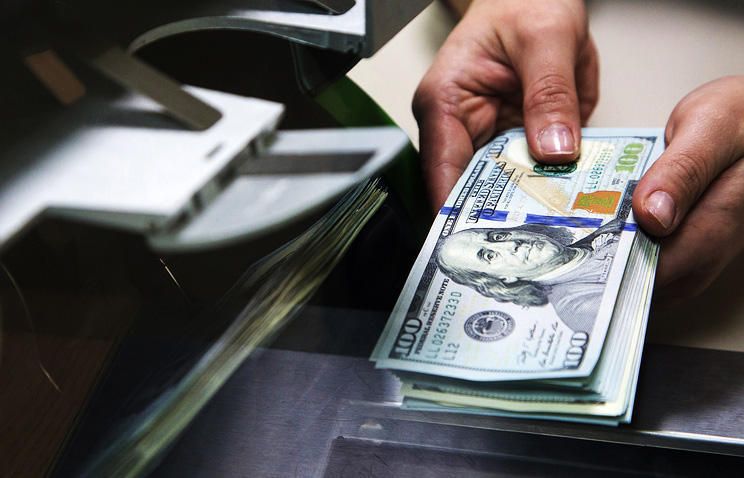
Read moreThere are solid economic grounds for the stability of the Azerbaijani manat against the US dollar until the end of 2026. The inflow of dollars generated in the country's external sector currently keeps the dollar supply strong. However, at the same time, persistently high inflation in the US and a stronger-than-expected labor market could lend renewed support to the global dollar. This is precisely where the main question arises for the manat: to what extent can the abundance of dollars in Azerbaijan compensate for the pressure created by the appreciation of the global dollar?
The indicators for the first half of 2026 show that Azerbaijan's foreign currency position is quite strong. In January–June, the country's foreign trade turnover reached $29.2 billion. Exports amounted to $19.3 billion, while imports stood at $9.8 billion. Thus, a positive balance of approximately $9.45 billion was generated in goods trade alone. This is one of the primary sources of foreign currency entering the country.
Another source is the remittances sent to the country by Azerbaijani citizens living abroad. In the first half of 2026, approximately $748 million in remittances flowed into Azerbaijan, while $207.8 million was sent out of the country. In other words, net inflows through this channel amounted to about $540 million. Although this figure is small compared to the trade surplus, it remains a factor positively affecting the foreign currency supply.
There is also notable dynamics in foreign direct investment (FDI). In the first half of the year, $3.6 billion in foreign direct investment flowed into the country's economy, while Azerbaijani residents made $5 billion in investments abroad. It would be incorrect to evaluate the $1.4 billion difference as a "net capital loss." This is because FDI is included in the Financial Account of the Balance of Payments—not the Current Account—and should be evaluated as an international redistribution of capital.
As a result of the large positive balance in foreign trade and other income flows, a surplus of $4.7 billion was formed in the Current Account. According to the Central Bank's explanation, it was precisely this surplus in the Current Account and dedollarization in the financial sector that ensured that supply exceeded demand in the foreign exchange market.
This situation was also reflected in the Central Bank's conduct. In August, the Central Bank purchased $1.5 billion from the market. During the January–August period, its foreign exchange reserves grew by $3.8 billion, or 33 percent, reaching $15.3 billion. This is an all-time high.
In other words, the issue in Azerbaijan right now is not a shortage of dollars. On the contrary, during a certain period, the supply of dollars in the market was so high that the Central Bank started buying dollars itself. Therefore, looking strictly at the domestic foreign currency balance, it is difficult to see a basis for the manat to come under serious pressure by the end of the year.
However, Azerbaijan alone does not determine the fate of the manat.
Recent data from the US could shift the position of the dollar in the global currency market. In August, nonfarm payrolls in the US increased by 162,000, whereas market expectations were for just 56,000. Thus, the result came in roughly three times higher than forecast. The unemployment rate also remained at 4.1 percent.
Inflation figures offer little comfort for the Fed either. In August, annual inflation (CPI) in the country stood at 3.4%, exceeding expectations. Core inflation (Core CPI) rose by 0.3% month-on-month, surpassing the market's forecast of a 0.2% increase. Despite annual core inflation slowing to 2.4%, the monthly acceleration indicates that inflationary pressures remain widespread. All of these figures remain above the Fed's medium-term target of 2% and heighten concerns that price growth is not fully under control.
For this reason, market expectations of a Fed rate hike have surged. On the eve of the September meeting, markets are pricing in a 25 basis point rate hike with roughly an 85–90 percent probability.
If the Fed raises rates, the yield on US assets increases, making the dollar more attractive to international investors. The return of a portion of capital from risky and emerging markets to the US could put pressure on national currencies.
Azerbaijan's advantage, however, lies in having its own dollar buffer against this global wave. Central Bank reserves of $15.3 billion, a large trade surplus, a positive Current Account balance of $4.7 billion, and a high supply of dollars in the market create a solid defensive line for the manat.
Therefore, two forces will collide in the coming months. Azerbaijan's domestic abundance of dollars will support the manat, while tighter US monetary policy and a strengthening global dollar will exert pressure in the opposite direction.
Based on current data, the first force still appears stronger. Consequently, the grounds remain solid for the stability of the manat through the end of the year.
Here we are to serve you with news right now. It does not cost much, but worth your attention.
Choose to support open, independent, quality journalism and subscribe on a monthly basis.
By subscribing to our online newspaper, you can have full digital access to all news, analysis, and much more.
You can also follow AzerNEWS on Twitter @AzerNewsAz or Facebook @AzerNewsNewspaper
Thank you!